A CX Wake-Up Call for Banking: Going Digital Isn't Enough; Customers Still Want Banks They Can Trust
Türkiye's banks are digitally strong, but the real difference comes down to the confidence they inspire when a customer runs into a problem.
Banking was one of the first industries to take digitalization seriously. Today, for most customers, the bank is no longer a branch; it is a phone screen. Money transfers, card management, loan applications, investments, limit changes, transaction disputes… Everything happens inside the app.
But QuestionPro’s Q1 2026 CX Benchmark report, which measures the US market, offers a very clear reminder: going digital is one thing; delivering a customer experience that inspires trust is another.
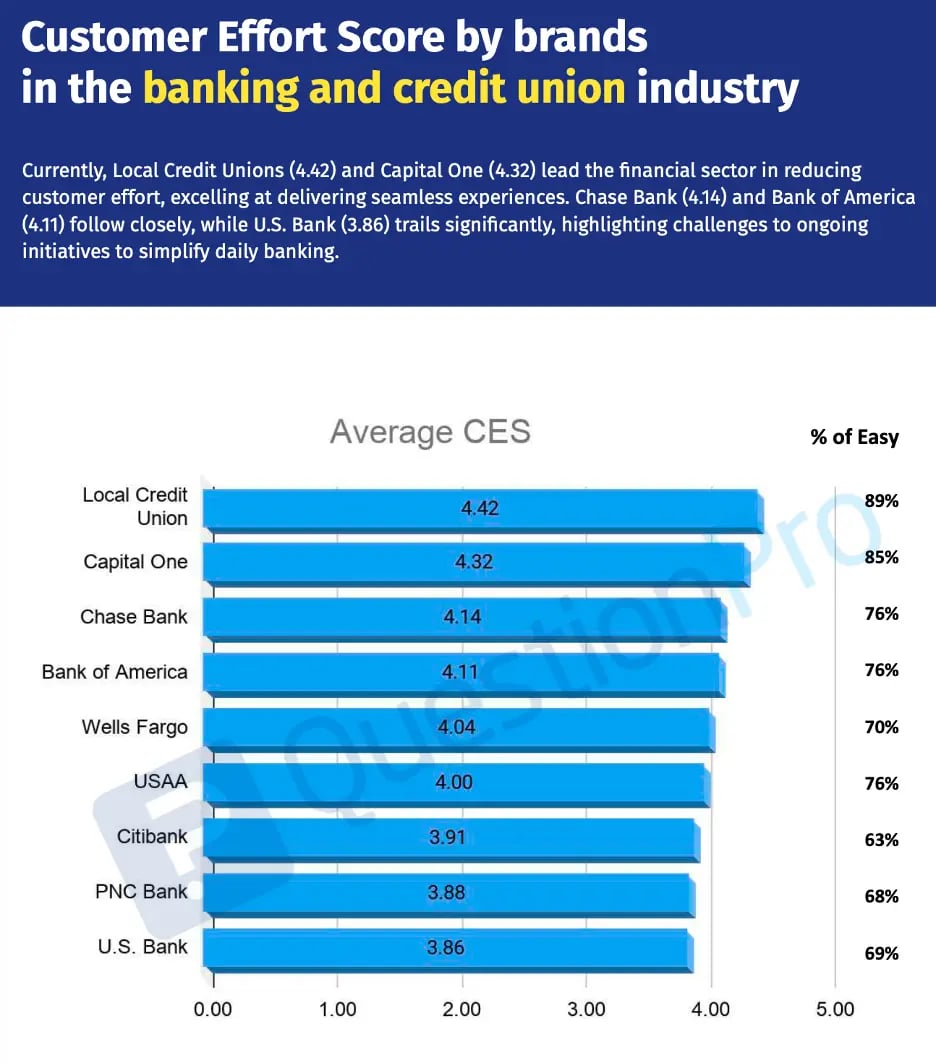
In the report, the Banking & Credit Unions category posts an NPS of 19, among the lowest of any sector. With CSAT at 72% and CES at 76%, it again ranks among the groups at the bottom. What’s more, banking’s NPS decline has now continued for a second consecutive quarter.
Customers don’t judge the banking app; they judge how secure they feel
Source: QuestionPro, Benchmarking CX Metrics by Industry and Brands in the U.S., Q1 2026
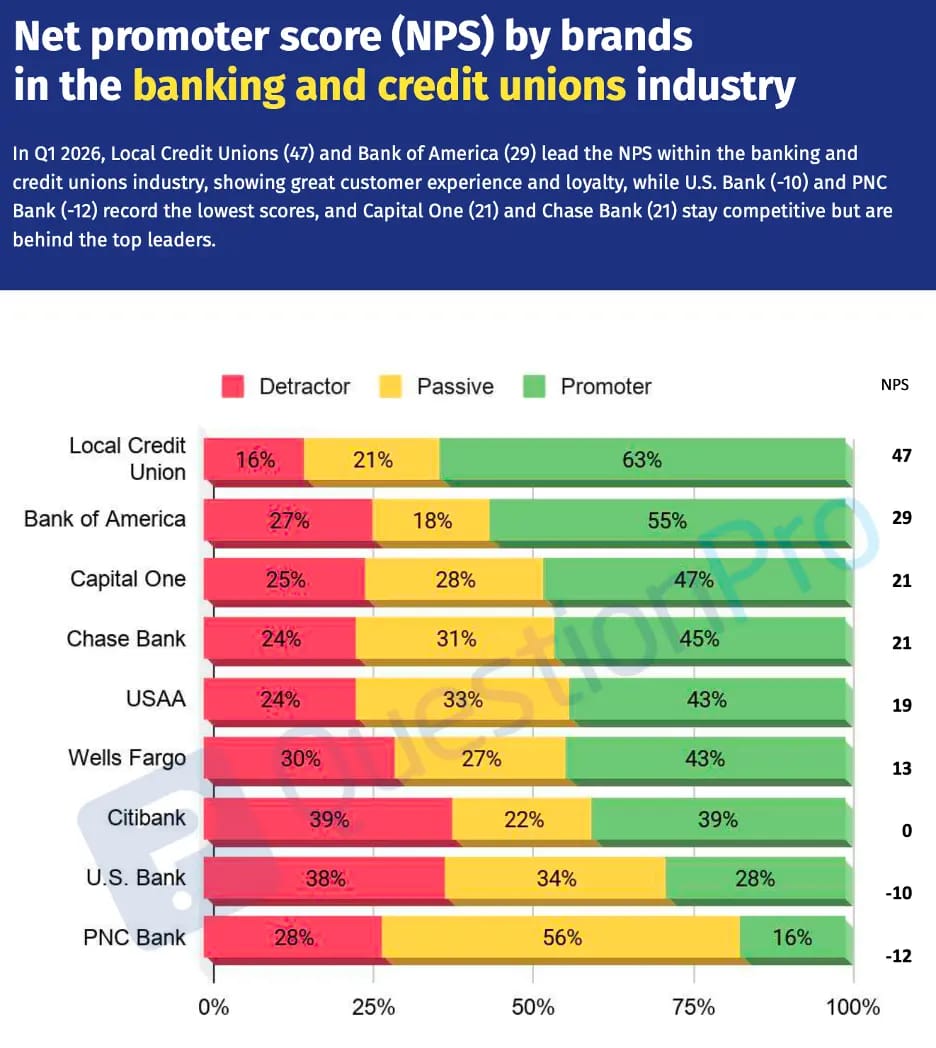
The brand-level picture is even more instructive. Local Credit Unions lead on NPS with 47. Bank of America follows with 29. U.S. Bank and PNC Bank, by contrast, are in negative territory at -10 and -12. The report notes that the strong performers stand out through their local community focus, service improvements, trust and digital banking experience.
When I consider what this means for Türkiye, I see a very important lesson. When it comes to digital product quality, Türkiye’s banking market is strong. According to the December 2025 digital banking statistics from the Banks Association of Türkiye (TBB), the number of active retail digital banking customers (not deduplicated) reached 122,729,000, while the total number of active digital customers stood at 127,677,000. (TBB)
But that is exactly why the risk is higher. Customers have gotten used to good apps. Their expectations have risen. “I can transfer money” is no longer enough to satisfy them. They look at how quickly their problems get resolved, how transparent fee information is and how safe they feel during a dispute.
Four critical friction points for Türkiye’s banks
In my view, four areas are especially critical for banking CX in Türkiye.
-
Fee and commission transparency. Customers react less to the fee itself than to being surprised by it later.
-
Transaction disputes and resolution ownership. A card charge, suspected fraud, a limit, a loan, a transfer or an investment transaction… When customers file a dispute, they don’t want to get lost in the process.
-
Channel continuity. If a process that starts in the app moves to the call center and then to a branch, and the customer has to explain everything all over again, the bank comes across as merely multichannel rather than digital.
-
Access to human contact. Self-service is good. But if customers can’t reach a human at a critical moment, self-service creates a sense of helplessness rather than freedom.
Source: QuestionPro, Benchmarking CX Metrics by Industry and Brands in the U.S., Q1 2026.
In banking, technology should be a support system, not a wall
The point I stressed in an earlier CX Bulletin article on T-Mobile’s NPS-centered transformation applies to banking too: technology should be positioned not as a wall in front of the customer but as a support system behind them.
AI in banking should be designed on the same principle. It should be used not to keep customers going in circles inside a chatbot, but to understand customer intent, pass context on to the representative, reduce fraud risk and shorten resolution time.
In banking, the question for 2026 should not be “How many features does our app offer?”
The real question is: “Do customers feel safe when they run into a problem?”
In financial services, trust is earned not through advertising but through the experience delivered in a moment of crisis.
This piece was first published in Turkish in CX Bulletin on April 28, 2026. English translation.